Tamil Nadu tightens GST compliance rules to curb Tax evasion on tobacco sales in the State
The Tamil Nadu Government’s reported amendments to Goods and Services Tax (GST) rules aim to strengthen tax administration, curb undervaluation and improve compliance in high-risk sectors, including tobacco, pan masala, online money gaming and casinos.
The measures focus on strengthening the valuation and reporting framework rather than necessarily increasing statutory GST rates. However, the precise legal position will depend on the applicable notifications, effective dates and enabling provisions.
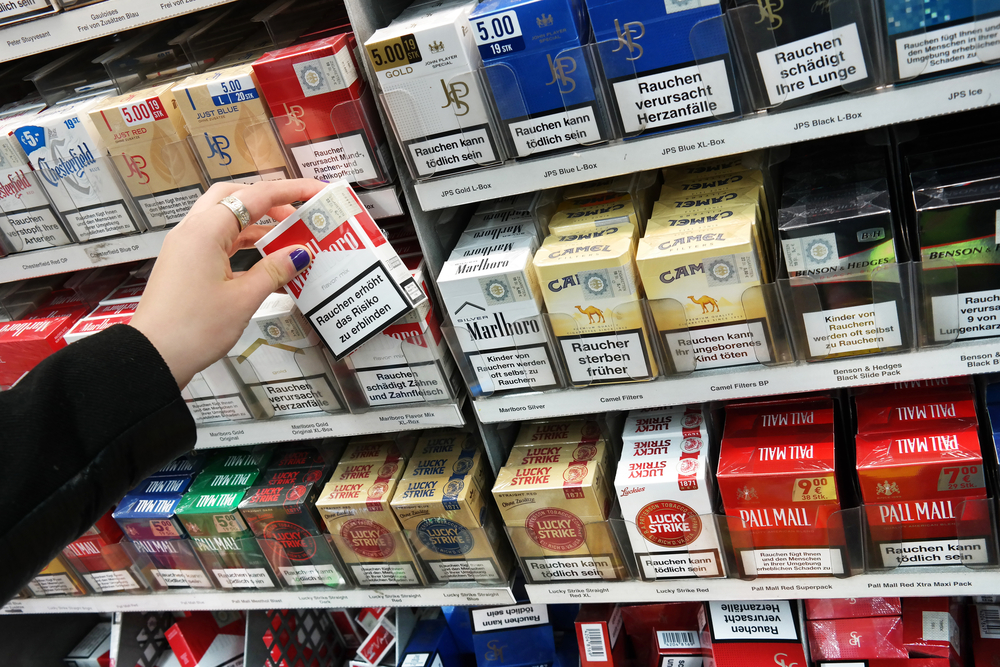
Under the reported changes, the taxable value of specified tobacco products and pan masala would be linked to their declared retail sale price, helping authorities address potential revenue leakage arising from artificial undervaluation.
Where multiple retail prices are declared, the highest applicable price would be considered, subject to the prescribed valuation rules.
For covered online money gaming transactions, GST valuation would be based on the full amount deposited or paid by players, including qualifying virtual digital assets.
Casino-related valuation would similarly cover amounts paid for chips, tokens, tickets and participation. Winnings reused without being withdrawn would not ordinarily be treated as a fresh deposit under the stated rules.
Overseas online money gaming operators and specified providers of online information and database access or retrieval services are subject to registration and GSTR-5A compliance requirements, including monthly returns due by the 20th of the following month.
These requirements are intended to strengthen GST administration for cross-border digital services and improve accountability among overseas operators serving Indian customers.
The reported measures seek to reduce opportunities for tax avoidance, improve compliance across domestic and overseas suppliers, and protect government revenues without necessarily raising statutory tax rates.
GST operates under a harmonised framework involving the Central GST Act, the Tamil Nadu GST Act and applicable rules. The relevant notifications and their effective dates need to be examined to establish the precise scope and implementation of the reported amendments.
More from Tamil Nadu
Lakhs of devotees throng Tiruchendur for grand Soorasamharam festival; 4100 Police deployed
Tamil Nadu Governor Arlekar extends Kandha Sashti greetings, highlights spiritual significance of Soorasamharam
Annamalai slams Vijay Govt. over Thiruparankundram Deepam row; demands implementation of HC orders
More from Politics
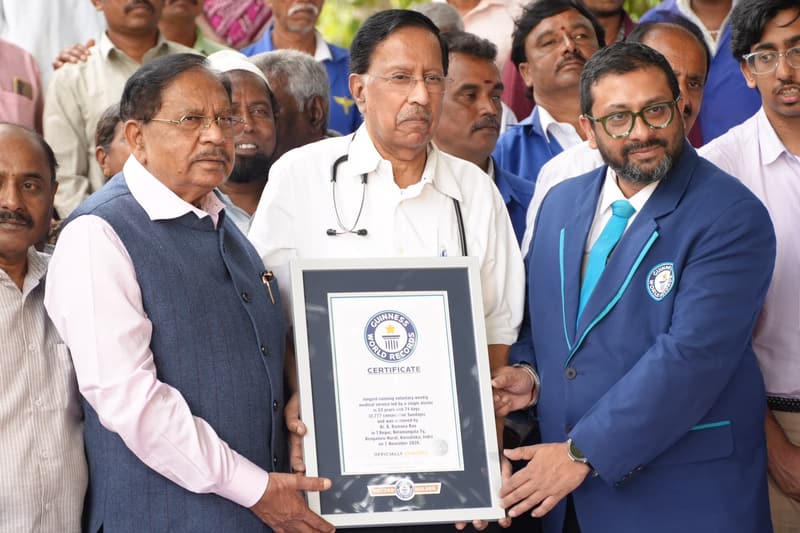
Padma Shri Dr B. Raman Rao enters Guinness World Records for treating over 33 lakh patients over 2777 Sundays
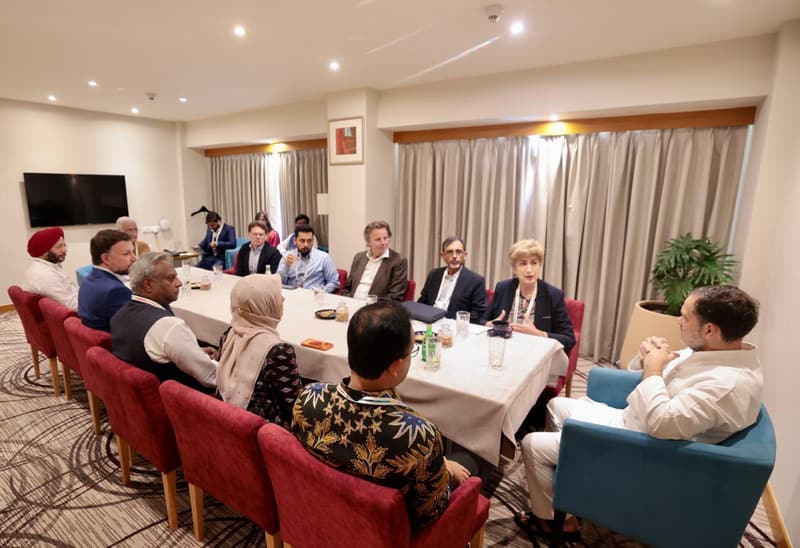
Rahul Gandhi calls for rethinking democracy and economic models amid growing influence of tech giants